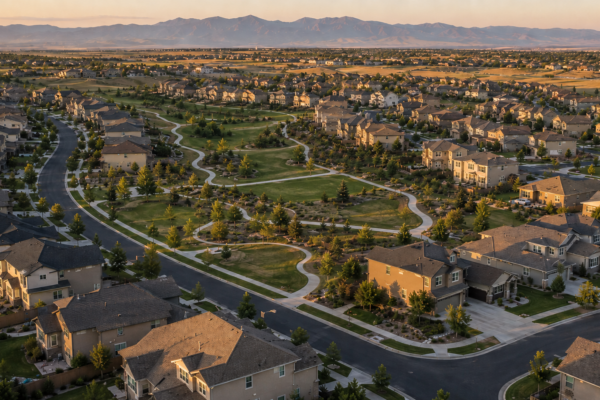
Anthem Highlands shows the hallmarks of a solid long-term hold: low inventory, strong resale demand, and a northwest metro location tied to major employment corridors. The key variable for $900K–$1M+ buyers is financing structure, since the 2026 Denver metro conforming loan limit of $862,500 means most purchases in this price band cross into jumbo territory.
Is Anthem Highlands a good long-term real estate investment?
Anthem Highlands is a strong long-term investment candidate in the northwest Denver metro, supported by low inventory, above-median price points, and consistent resale demand. The most important variable for buyers in the $900K–$1M+ range is financing structure: the 2026 conforming loan limit for Broomfield County is $862,500, meaning most purchases here require a jumbo loan unless the buyer puts enough down to stay below that threshold. Reading the market data correctly, and structuring your financing intentionally, is what separates a disciplined investment from an expensive mistake.
Key Takeaways
- The 2026 conforming loan limit for Broomfield County (and all Denver metro counties) is $862,500 for a one-unit property, according to AlpineBanker’s 2026 Colorado loan limit guide; any loan above that amount is jumbo.
- A national portal reported a median listing price of $922,000 for Anthem Highlands as of early 2026, with a year-over-year change of –5.39% in listing prices, a signal that list prices softened even as closed-sale conditions remained competitive.
- Recent local MLS data for the Wildgrass area (trailing ~90 days, September 2026) shows a median sale price of approximately $1,098,000 and a median of approximately 24 days on market, with only 2 active listings, a tight supply picture across this northwest Broomfield corridor.
- A May 2026 Broomfield county update reported single-family home prices near $675,000 and days on market around 11 days, confirming that Anthem Highlands’ $900K+ price point sits well above the broader city median.
- Buyers at $900K with 10% down can stay conforming; buyers at $1M with 10% down carry a $900K loan and cross into jumbo; that distinction directly affects underwriting requirements, rate behavior, and investment return.
What do the current market numbers actually tell you about Anthem Highlands?
Before you can evaluate an investment, you need to read the data correctly. And in Anthem Highlands, that means looking past portal headlines.
A Realtor.com neighborhood page for Anthem Highlands, last updated April 2026 and reflecting February 2026 conditions, showed a median listing price of $922,000 with a year-over-year change of –5.39% and a three-year change of –2.95%. That sounds bearish at first glance. But here’s the nuance: that figure tracks listing prices, not closed sales. List prices can drift down when sellers test the market and reprice; closed-sale data tells a different story. I always tell clients to go to closed-sale comps first, not portal listing stats, when they’re evaluating whether a neighborhood is holding value.
The same Realtor.com page reported $235 per square foot and 32 median days on market in that February snapshot, with 7 active listings. That’s a relatively tight, balanced-to-competitive picture for a luxury subdivision. Current MLS data shows Anthem Highlands homes closing at approximately $232 per square foot, closely tracking that earlier snapshot.
Zooming out to the broader northwest Broomfield corridor, recent local MLS data (trailing roughly 90 days, as of September 2026) shows a median sale price of approximately $1,098,000 in the Wildgrass area and a median of approximately 24 days on market, with only 2 active listings. That’s an extremely thin supply environment. For context, a May 2026 Broomfield market update put the county-wide single-family median near $675,000 with days on market around 11 days, though January 2026 started at 56 days before spring activity compressed the timeline. Anthem Highlands, with its $900K+ price points, sits well above both of those benchmarks.
Here’s a quick look at recent closed-sale data across two northwest Broomfield areas:
| Area | Median Sale Price | Median Days on Market |
|---|---|---|
| Wildgrass | ~$1,098,000 | ~24 |
| McKay Landing | ~$942,500 | ~12 |
These are area-level medians from aggregated MLS data, trailing roughly 90 days as of September 2026. An individual home’s value depends on condition, street, build year, and timing. But the pattern is consistent: northwest Broomfield is a low-inventory market where well-priced homes move quickly, especially in the spring and summer months. That matters for how you model holding periods and liquidity risk.
What does inventory actually signal at the $900K–$1M price band?
Low inventory across the market doesn’t mean every price band behaves the same way. In Anthem Highlands, the $900K–$1M range shows more balanced conditions than the sub-$800K segment. That means buyers in this band have slightly more negotiating room, and sellers should expect longer marketing times than they might at lower price points.
For an investor, this is actually useful information. More balanced conditions at the entry point of the luxury segment means you’re less likely to overpay in a bidding frenzy, but you also need to model a realistic hold period if you ever need to sell. A well-presented home at a surgical price will still move. A home that’s overpriced by $30K–$40K in this band will sit, and sitting costs you money.
A spring 2026 Broomfield market update described the broader county as a “textbook balanced market” with 3.3 months of supply. A tighter picture emerged as spring activity picked up, with Broomfield homes selling in a median of 11 days in May and closing at 100% of asking price. The divergence between those two snapshots reflects different time slices and property types. The takeaway for an Anthem investor: conditions have been fluid in 2026, and real-time, subdivision-level data matters far more than county-wide averages.
How jumbo vs conforming financing shapes your investment math
This is the part most buyers overlook until they’re already in contract. And in Anthem Highlands, it’s the single most consequential financial variable you’ll face.
According to AlpineBanker’s 2026 Colorado conforming loan limit guide, the 2026 limit for a one-unit property in Broomfield County, and across all ten Denver metro counties, including Adams, Denver, Jefferson, and Douglas, is $862,500. Any loan above that threshold is jumbo. This is the most current published figure available as of September 2026.
Here’s where that line lands in practical terms for Anthem Highlands buyers:
- Purchase at $900K, 10% down: Loan amount is $810,000. That stays below $862,500; conforming financing is available.
- Purchase at $1M, 10% down: Loan amount is $900,000. That crosses the conforming cap; jumbo financing required.
- Purchase at $1M, 15% down: Loan amount is $850,000. Still under the cap; conforming is possible with the right lender and program.
Why does this matter for investment returns? Jumbo loans come with stricter underwriting: higher credit score thresholds, larger cash reserve requirements, and different rate behavior compared to conforming loans backed by Fannie Mae or Freddie Mac. Jumbo rates don’t always move in lockstep with the conforming market, and in periods of rate volatility, that spread can widen. That affects your carrying cost, your cash-on-cash return if you’re holding as a rental, and your refinance options down the road.
Investors who are sensitive to underwriting complexity often structure their down payment specifically to stay at or below $862,500. Others accept the jumbo threshold to preserve liquidity, especially if they’re deploying capital across multiple properties. Neither approach is universally right; it depends on your balance sheet, your rate environment, and your investment horizon. Verify your specific numbers with your lender before you write an offer; the financing structure should be decided before you’re in contract, not after.
For a deeper look at how interest rate conditions affect Anthem Highlands values specifically, I’d point you to this post on what happens to Anthem Highlands home values if rates stay elevated; it’s directly relevant to your return modeling.
What about the investment case beyond financing?
Location fundamentals still drive long-term real estate returns, and Anthem Highlands has a credible story there. The neighborhood sits in north Broomfield, inside the northwest Denver metro corridor, with access to Denver, Boulder, and the Interlocken/US-36 employment hub. Master-planned community amenities, newer construction stock, and consistent buyer demand from the professional workforce in this corridor support both resale value and long-term rental potential.
That said, rental yields at the $900K–$1M+ acquisition cost require careful underwriting. Monthly gross rents in this segment rarely produce the cap rates you’d find at lower price points. Most investors in Anthem Highlands are buying for appreciation and quality-of-life optionality, not cash flow. If your return model depends on rental income to service the debt, run those numbers conservatively and verify them with a local property manager before you commit.
Recent Broomfield MLS data shows single-family homes selling at 100% of asking price with 1.8 months of supply, a seller-favored environment at the county level. For Anthem Highlands, where the price band is higher and conditions are more balanced with a sale-to-list ratio averaging around 98.3%, your offer strategy and pricing discipline matter more than they would in a hotter segment. That’s where having a local agent who tracks subdivision-level data, not just county averages, makes a real difference.
If you want to understand what the full purchase cost looks like before you model your returns, this breakdown of the true cost of buying a home in Anthem Highlands walks through what buyers in this price range should anticipate.
Frequently Asked Questions
Is Anthem Highlands a good long-term investment compared to other Broomfield neighborhoods?
Anthem Highlands holds up well as a long-term investment relative to the broader Broomfield market, primarily because of its low inventory, above-median price positioning, and location in the northwest metro employment corridor. The tradeoff is that higher acquisition costs compress rental yields, and the $900K–$1M price band shows more balanced conditions than lower-priced segments, so appreciation is less automatic than in a tighter market. Closed-sale data and absorption rates at the subdivision level are more reliable indicators than county-wide averages when comparing neighborhoods.
How does the 2026 Denver metro conforming loan limit affect my mortgage if I’m buying at $950K in Anthem Highlands?
The 2026 conforming loan limit for a one-unit property in Broomfield County is $862,500, according to AlpineBanker’s 2026 Colorado loan limit guide. At a $950K purchase price, whether you stay conforming depends entirely on your down payment: a 10% down payment leaves you with a $855,000 loan, which is just under the cap; anything less pushes you into jumbo territory. Jumbo loans carry stricter credit and reserve requirements and may behave differently on rate than conforming loans, so structuring your down payment intentionally before you go under contract is essential.
Can I still stay conforming with a big enough down payment on a $1M Anthem Highlands home?
Yes, with enough down. To keep your loan at or below $862,500 on a $1M purchase, you’d need to put down at least $137,500, roughly 14% down. Some buyers in this price band adjust their down payment specifically to stay conforming and access easier underwriting and more predictable rate behavior. Verify the math with your lender early, because the conforming-versus-jumbo decision affects not just your rate but your reserve requirements and long-term refinance flexibility.
Have prices in Anthem Highlands gone up or down over the last year?
The picture is mixed depending on which data you use. A Realtor.com neighborhood page for Anthem Highlands, reflecting February 2026 conditions, showed a year-over-year change of –5.39% in median listing prices. However, listing prices and closed-sale prices tell different stories; list prices can soften when sellers test the market and reprice, while closed-sale data may reflect stronger conditions. The most reliable approach is to look at subdivision-level closed-sale comps rather than portal listing statistics, which is exactly the analysis I run for clients before they make an offer.
Why does the $900K–$1M price band in Anthem show more balanced conditions than the rest of the neighborhood?
Higher price points always carry a smaller pool of qualified buyers, which naturally extends days on market and gives buyers slightly more negotiating leverage than they’d find in tighter segments. In Anthem Highlands, the $900K–$1M band also coincides with the jumbo financing threshold, which adds an underwriting hurdle that can slow buyer decision-making. This doesn’t make the segment a bad investment; it means pricing discipline and presentation quality matter more here than they would at lower price points, where demand is broader and competition sharper.
The bottom line on Anthem Highlands as an investment
The fundamentals are there: low inventory, a high-demand northwest metro location, and a price point that holds up well against the broader Broomfield market. The variable that most investors underestimate is the jumbo financing threshold at $862,500; structuring your down payment around that line is one of the highest-leverage decisions you’ll make before you close.
If you’re evaluating Anthem Highlands as a purchase or investment and want to run the actual numbers for your situation, I’m happy to pull subdivision-level closed-sale data and walk through the financing scenarios with you. Reach out to schedule a conversation; no pressure, just data.
By contacting The North Star Team, you agree to be contacted via call, email, and text for real estate services. Reply ‘stop’ to opt out. Message and data rates may apply.
About John Grandt
John Grandt is a Broomfield, Colorado REALTOR® with Real Broker and founder of The North Star Team. A full-time agent since 2017 with more than $100 million in career sales across the Denver metro, he helps families buy and sell homes with a data-driven, full-service approach and holds the CLHMS and RENE designations.
Real Broker, LLC · 720.351.8488
Equal Housing Opportunity. John Grandt is a licensed Colorado real estate broker with Real Broker, LLC, regulated by the Colorado Division of Real Estate. This article is general market information only, not legal, tax, or financial advice. Confirm your specific numbers with your title company, tax advisor, or lender before making any transaction decisions.