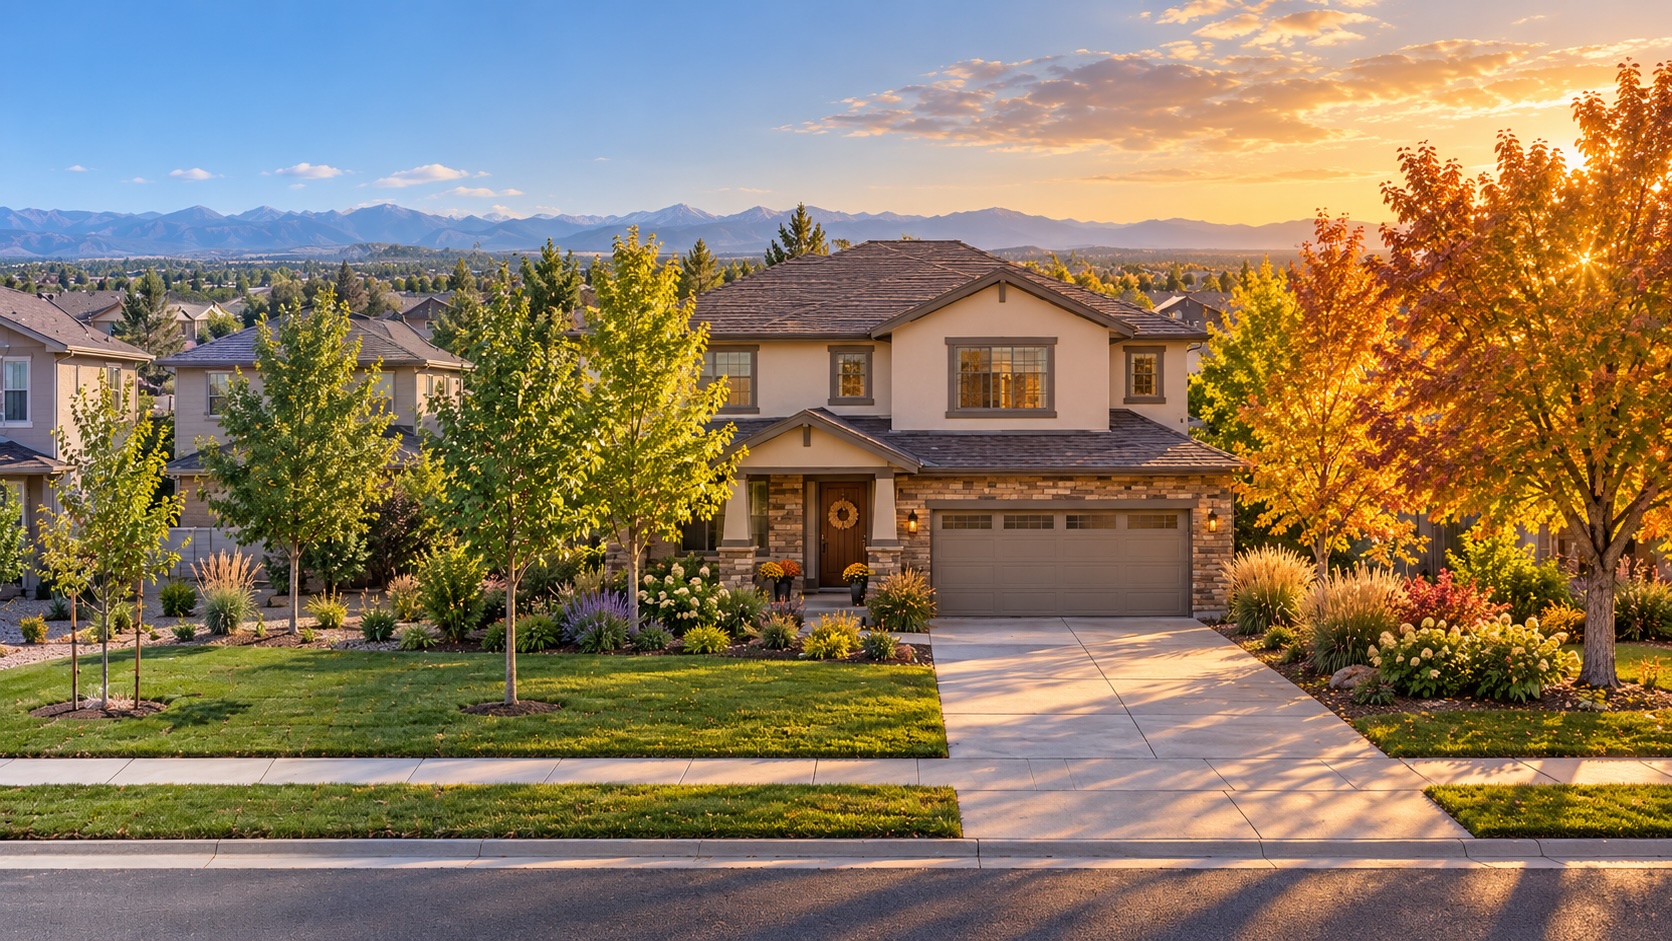
How much equity do Broomfield homeowners have after the last 5 to 10 years of ownership?
If you bought a typical Broomfield single-family home 10 years ago with 20% down, you likely have around $500,000 in equity today. Broomfield home values rose about 75% from 2016 to 2025, according to the Federal Housing Finance Agency’s house price index, and a decade of mortgage payments has paid down a meaningful part of your loan on top of that.
Why This Matters Right Now in Broomfield
You might not think about your home equity on a daily basis. But if you’re considering a move-up purchase, a relocation, or simply wondering what your next chapter looks like, that number changes everything.
Broomfield single-family homes sold for an average of about $792,000 through the first nine months of 2026, per REcolorado MLS data. If you have owned your home for five years or more, a large share of that value is likely yours.
I’ve been helping Broomfield homeowners since 2017 and have closed over 125 transactions, and I can tell you that you may be underestimating how much wealth you’ve built. The conversation usually shifts the moment we sit down and map out the actual numbers together. So let me walk you through what your equity likely looks like based on when you bought.
What 10 Years of Broomfield Home Values Look Like
Let’s start with the big picture. The Federal Housing Finance Agency tracks home values in Broomfield County using repeat sales of the same homes, which makes it a good way to see how much a specific house has gained over time.
Based on that index, here is roughly what a Broomfield home worth about $792,000 today would have been worth in each year:
- In 2016, it would have been worth about $452,000.
- In 2017, it would have been worth about $493,000.
- In 2018, it would have been worth about $531,000.
- In 2019, it would have been worth about $548,000.
- In 2020, it would have been worth about $562,000.
- In 2021, it would have been worth about $640,000.
- In 2022, it would have been worth about $741,000.
- In 2023, it would have been worth about $761,000.
- In 2024, it would have been worth about $779,000.
That is an increase of about 75% from 2016 to 2025. If you bought a home like this in 2016, it has gained roughly $340,000 in value from appreciation alone.
The biggest jumps came in 2021 and 2022. Since then, values have grown much more slowly. The FHFA index rose less than 7% from 2022 to 2025, and the average Broomfield single-family sale price has stayed close to $790,000 every year since 2023, per MLS data.
How Your Broomfield Equity Breaks Down by Purchase Year
Your equity depends on three things: when you bought, how much you put down, and how much of your loan you’ve paid off. The estimates below assume a home worth about $792,000 today, a 20% down payment, and a 30-year fixed loan at the average Freddie Mac rate for the year you bought.
If You Bought Around 2016
You would have paid about $452,000, and with 20% down your loan would have started near $362,000. After about 10 years of payments at a rate near 3.65%, your balance would be around $281,000. With your home worth about $792,000 today, your equity would be roughly $511,000. That’s a life-changing number if you’re thinking about moving up to a home in Anthem Highlands or The Broadlands.
If You Bought Around 2019
You would have paid about $548,000, and your loan would have started near $439,000. After about seven years at a rate near 3.94%, your balance would be around $377,000, which leaves you with roughly $415,000 in equity.
If You Bought in 2021
You would have paid about $640,000, and your loan would have started near $512,000. After about five years at a rate near 2.96%, your balance would be around $455,000, which leaves you with roughly $337,000 in equity. Your home has gained about $152,000 in value, and your low rate means more of each payment has gone to your balance.
If You Bought in 2022
This is where I get the most questions. If you bought near the 2022 peak, you would have paid about $741,000, and your loan would have started near $593,000 at a rate near 5.34%. After about four years, your balance would be around $557,000. Values have still risen since 2022, so your equity would be roughly $235,000. Most of that came from your down payment, with about $51,000 from appreciation and about $36,000 from paying down your loan.
What I tell my clients is this: even in a slower market, you’re building equity with every mortgage payment, and that adds up faster than most people realize.
Keep in mind that equity is not the same as the cash you would walk away with. If you sell, your selling costs, including commissions and closing costs, come out of that equity. On a $792,000 home, every 1% in costs is about $7,900, so it is worth running your real net number before you make a decision.
Why Broomfield Homes Have Held Their Value
Broomfield values have held up well, even as the pace of growth has slowed.
First, the number of homes for sale is still limited. Broomfield had 276 single-family homes for sale at the end of September 2026, down from 302 a year earlier, which works out to about 2.8 months of supply, per MLS data.
Second, buyers are still buying. Through September, 868 single-family homes sold in Broomfield, up about 9% from the same period in 2025. The average sale price was up about 2.3%.
Third, neighborhood matters. If you own in Anthem Highlands, your equity may be even stronger. Single-family homes in the Anthem Highlands area sold for an average of about $1,007,000 through September 2026, per MLS data.
That said, the market has cooled from its peak. The median Broomfield single-family home took 32 days to sell in September, the longest September median since 2021, and homes sold for about 97% of their original asking price. Your equity is real, but how much of it you keep when you sell depends on pricing your home correctly from the start.
What You Can Actually Do With Your Broomfield Equity
Here’s where the conversation gets practical. Having significant equity is only powerful if you know how to use it.
Sell and Move Up
This is where I spend most of my time with clients. If you’re thinking about moving up, the equity in your current home can become the down payment on your next one. With $300,000 or more in equity, a 20% down payment on a $900,000 home is within reach without touching your savings. Understanding how to price your current home is the first step in turning that equity into your next purchase.
Keep in mind that today’s mortgage rates are higher than many current owners are used to. Freddie Mac reported the average 30-year fixed rate at 7.32% as of October 22, 2026, so a larger down payment from your equity can make a real difference in your monthly payment on your next home.
Borrow Against Your Equity Without Selling
If you want to stay, a home equity loan or line of credit lets you borrow against your equity. Most lenders let you borrow until your total loans reach about 80% to 85% of your home’s value. Rates and terms vary by lender and credit profile, so compare offers before you commit.
Hold and Keep Building
Broomfield values have been close to flat since 2023, but they have not fallen, and every payment you make still builds equity. If your timeline extends several more years, holding is a reasonable choice.
How to Know Your Exact Equity in Broomfield
A blog post can give you ranges. Only a pricing analysis based on your specific home, neighborhood, condition, and upgrades will give you your real number.
What I always recommend is sitting down with someone who knows Broomfield’s neighborhoods inside and out. The difference between a home in Anthem Highlands and a home a few miles away can be hundreds of thousands of dollars, and a generic online estimate does not capture that well.
As a Certified Luxury Home Marketing Specialist and Real Estate Negotiation Expert, I focus on helping you understand your home’s value down to the neighborhood and even the street. With 15 five-star reviews from past clients, I take this part of the process seriously, because getting the number right is the foundation of every smart selling decision.
Frequently Asked Questions
If you bought a typical Broomfield single-family home around 2016 with 20% down, you likely have roughly $500,000 in equity today. That estimate assumes a home worth about $792,000 now, a purchase price near $452,000 based on the Federal Housing Finance Agency’s house price index, and 10 years of payments on a 30-year loan.
If you bought around 2021 with 20% down, you likely have roughly $337,000 in equity, assuming a home worth about $792,000 today. About $152,000 of that came from appreciation, and the rest came from your down payment and loan paydown.
Yes. Broomfield values rose sharply in 2021 and 2022, but the Federal Housing Finance Agency index rose less than 7% from 2022 to 2025. The average Broomfield single-family sale price has stayed close to $790,000 each year since 2023, per MLS data.
Yes. Values have still risen modestly since 2022, so if you bought with 20% down, you likely have roughly $235,000 in equity today. Most of that is your down payment, with the rest coming from appreciation and four years of loan payments.
Broomfield single-family homes sold for an average of about $792,000 from January through September 2026, and the median sale price in September was $715,000, per MLS data. Prices vary widely by neighborhood, and Anthem Highlands area homes averaged about $1,007,000.
Yes. A home equity loan or line of credit lets you borrow against your equity. Most lenders let you borrow until your total loans reach about 80% to 85% of your home’s value, and rates and terms vary by lender and credit profile.
The median Broomfield single-family home that sold in September 2026 took 32 days to sell, and the average was 45 days, per MLS data. That median is the longest for any September since 2021, which is why pricing your home correctly matters.
The data does not point that way. Broomfield had about 2.8 months of single-family supply at the end of September 2026, sales through September were up about 9% from last year, and the average sale price was up about 2.3%, per MLS data. The market is slower than in 2021, but values have held.
No. Your selling costs, including commissions and closing costs, come out of your equity when you sell. On a $792,000 home, every 1% in costs is about $7,900, so it is worth calculating your net proceeds before you decide.
Start with a pricing analysis of your specific home from someone who knows your neighborhood. Online estimates often miss upgrades, condition, and neighborhood-level demand, and knowing your precise number is the first step toward a smart move-up plan.
The Bottom Line
If you’ve owned a home in Broomfield for five to 10 years, you are likely sitting on meaningful wealth. Depending on when you bought, a typical Broomfield single-family homeowner who put 20% down has roughly $235,000 to $510,000 in equity today.
That equity is yours. Whether you use it to move up to Anthem Highlands, fund a renovation, or plan your next life stage, the first step is knowing your exact number.
I’m John Grandt with The North Star Team Powered by Real Broker, and I’ve spent the years since 2017 and more than 125 transactions helping Broomfield families understand and use their home equity. If you want a no-pressure conversation about what your home is actually worth today, call me at 720.351.8488, and let’s put real numbers on the table and figure out your best next move.